
Original Research
Extreme Returns and Idiosyncratic Volatility: Evidence from the Egyptian Stock Exchange


- Abstract
- Full text
- Metrics
This paper examines how expected stock returns are cross-sectionally linked to both the peak daily return observed over a month (MAX) and the idiosyncratic volatility (IVOL) in the Egyptian Stock Market from June 2018 to June 2022. MAX3 is also used as an alternative to the average of the three highest daily returns over the past month (t-1). The study utilizes a number of control variables, such as Short-term reversal (REVi,t), Momentum (MOMi,t), Market Beta (BETAi,t), and market capitalization (SIZEi,t). This paper documents a significant and positive IVOL effect in bivariate analysis, indicating that the most volatile stocks tend to yield higher returns in the subsequent month. However, this IVOL effect proves to be highly sensitive, losing its statistical significance once SIZEi,t and other control variables are introduced simultaneously. In contrast, the relationship between MAX, MAX3 and the subsequent month’s return is consistently not statistically significant when the other six variables are taken into account either individually or simultaneously. Therefore, the MAX effect is not evident in the Egyptian Stock Market, while the IVOL effect is conditional and dependent on other firm characteristics.
|
Extreme Returns and Idiosyncratic Volatility: Evidence from the Egyptian Stock Exchange |
|
Sadat Academy for Management Sciences, Cairo |
|||
|
Received: 03 February 2026 |
Revised: 11 April 2026 |
Accepted: 22 April 2026 |
|
|
|
ABSTRACT This paper examines how expected stock returns are cross-sectionally linked to both the peak daily return observed over a month (MAX) and the idiosyncratic volatility (IVOL) in the Egyptian Stock Market from June 2018 to June 2022. MAX3 is also used as an alternative to the average of the three highest daily returns over the past month (t-1). The study utilizes a number of control variables, such as Short-term reversal (REVi,t), Momentum (MOMi,t), Market Beta (BETAi,t), and market capitalization (SIZEi,t). This paper documents a significant and positive IVOL effect in bivariate analysis, indicating that the most volatile stocks tend to yield higher returns in the subsequent month. However, this IVOL effect proves to be highly sensitive, losing its statistical significance once SIZEi,t and other control variables are introduced simultaneously. In contrast, the relationship between MAX, MAX3 and the subsequent month’s return is consistently not statistically significant when the other six variables are taken into account either individually or simultaneously. Therefore, the MAX effect is not evident in the Egyptian Stock Market, while the IVOL effect is conditional and dependent on other firm characteristics. |
||
|
Keywords: Maximum Daily Return, Idiosyncratic Volatility, Egyptian Stock Exchange, Cross-Sectional Regression Analysis,
*Corresponding author:
JEL classification D53; E22; G11; G30; G32 |
|||
Several recent studies have reported that the highest daily return a stock achieved in the previous month (MAX) tends to be inversely associated with the return it generates in the following month. Bali et al. (2011) show that stocks exhibiting elevated MAX values generally deliver weaker returns in the months that follow than stocks with low MAX in the US. Stock market; they called this phenomenon Extreme Return. In financial practice, the MAX measure serves as an indicator that helps analysts assess how extreme price movements contribute to the overall performance of an investment and provides information about the profit you can obtain from the investment during the investment period. So, Extreme Return can be considered an important indicator for investors in making good investment decisions because it provides information about potential benefits and the level of risk of an investment.
A substantial body of literature has highlighted the negative MAX effect across various equity markets. For example, Brunnermeier et al. (2007) showed that investors tend to overrate their anticipated investment returns due to optimistic beliefs, ultimately resulting in lower average stock returns. Annaert et al. (2013) confirmed the presence of the MAX effect in the European stock market, finding that stocks with high positive returns have lower average returns in the future. Walkshäusl (2014) also documented the negative MAX effect in the European stock markets. Hur and Singh’s (2016) results on U.S. markets indicated that the MAX effect concerns how investor attention and risk preferences influence decision-making. Recently, Dimitry and Nugroho (2023) found a significant negative cross-sectional relation between the stock’s maximum daily return over the prior month and expected returns in the Indonesia Stock Exchange.
Ang et al. (2006) were among the first to highlight the pattern whereby firm-specific volatility (IVOL) exhibits a distinctive relationship with expected returns. In the U.S. and the other 23 developed stock markets, stocks with higher IVOL tend to have significantly lower future returns. This empirical regularity stands at odds with conventional financial theory, which posits that such firm-level risk should not command a return premium since it can be diversified away, and classic asset pricing models such as the Capital Asset Pricing Model (CAPM) suggest that the IVOL should not be priced as it could be avoided through diversification. A major point in asset pricing research is that the MAX effect mainly explains stock returns. Specifically, Bali et al. (2011) demonstrated that when your account for the maximum daily return (MAX), the well-known negative link between idiosyncratic volatility (IVOL) and expected returns in the U.S. market becomes much weaker. This key finding has been supported by subsequent studies in other developed markets, including Europe (Annaert et al., 2013; Walkshäusl, 2014), Australia (Zhong & Gray, 2016), and recent research focused on the U.S. (Egginton & Hur, 2018).
This study will employ methods similar to those of Bali et al. (2011) to investigate the importance of the maximum daily return over a month (MAX) and idiosyncratic volatility (IVOL) in explaining the cross-section of expected returns in the Egyptian Stock Market. Following Bali et al. (2011), several variables are also included as control variables, these variables are market capitalization (size), Short-term reversal (rev), Momentum (mom), and Market Beta (beta). This study will provide the first empirical evidence examining the role of the MAX and IVOL effects in asset pricing in the Egyptian Stock Market. Previous studies mostly focused on several developed markets. Hence, this study will focus on one of the emerging markets, which is the Egyptian stock market.
Literature Review
The MAX Effect
The relationship between a stock’s prior maximum daily return and its subsequent performance, commonly referred to as the MAX effect, has been a key area of interest in financial literature since the seminal work of Bali et al. (2011). They established a robust, statistically significant negative relation between the stock’s maximum daily return over the prior month (MAX) and its subsequent monthly returns in the U.S. stock market. According to this data, stocks with abnormally high MAX levels typically produce lower subsequent returns than those with more moderate extreme daily gains. Importantly, Bali et al. (2011) also showed that the MAX effect persisted after controlling for conventional variables such as size, momentum, short-term reversals, book-to-market, illiquidity, and skewness. Similar findings confirming this significant negative cross-sectional relation in the U.S. market were reported by Annaert et al. (2013), using a comparable set of control variables.
The MAX effect has demonstrated significant global generalizability. Walkshäusl (2014) provided strong supportive evidence of a negative relationship across a sample of European stock markets from 1990 to 2011. Similarly, Zhong and Gray (2016) found a strong, significant negative MAX effect in the Australian stock market, arguing that it indicates the degree to which assets are mispriced rather than having a risk-based interpretation.
Furthermore, the robustness of the MAX effect appears even stronger in emerging markets. Seif et al. (2018) documented strong evidence of the negative MAX effect in several developed emerging markets. They found this effect to be highly significant compared with results from U.S. financial markets. This finding was echoed by Wu et al. (2019), who observed a strong inverse relationship between the maximum daily return and subsequent asset returns across five major African stock exchanges, and by Bi et al. (2022), who confirmed the presence of the effect in the Chinese stock market and linked it to large transaction volume.
Despite the pervasive evidence of a negative MAX effect, its significance remains contingent upon market context. Kashif and Leirvik (2022) examined the MAX effect in the Norwegian stock market and initially found it to be insignificant. However, the effect became statistically significant only when controlling for specific downturns in the oil market, suggesting that unique macroeconomic factors can influence the predictability of the extreme return measure.
Idiosyncratic Volatility
The link connecting idiosyncratic volatility (IVOL) with expected stock returns has been one of the most debated topics in finance, often referred to as the IVOL puzzle. Foundational studies in the U.S. market documented a counterintuitive finding: a negative relationship between IVOL and expected returns. Ang et al. (2006) used the Fama and French (1993) model to measure idiosyncratic stock return volatility and found a strong negative link, documenting that stocks with lagged IVOL exhibit very low future returns, suggesting they were mispriced by the Fama and French (1993) model. This negative relationship was also confirmed in emerging markets; for instance, Drew et al. (2004) found the IVOL effect at the Shanghai Stock Exchange, showing that stocks with low IVOL achieved returns higher than those with high IVOL.
Contrary to the negative puzzle, a number of studies showed evidence of a positive correlation, indicating that IVOL functions as a typical risk factor. According to Fu (2009), in the U.S. stock market, stocks with high IVOL produced high expected returns. This positive IVOL effect was validated by Huang (2009), who discovered that it is more pronounced in stocks with high cash flow volatility. Additionally, Qadan (2019) found a positive correlation between IVOL and expected returns, linking the effect to investor sentiment, using the Fama-French five-factor model to calculate IVOL in the U.S. market. Given this controversy, Bali and Cakici (2008) found that IVOL and expected returns in the U.S. stock market did not correlate significantly, underscoring the fragility of the effect.
The IVOL puzzle has been explained by various scholars in terms of arbitrage risk and other interactions between different factors. According to Stambaugh et al. (2015), the IVOL puzzle represents arbitrage risk, and they found that while overvalued stocks experience a more significant negative impact from IVOL than undervalued stocks, positively experience; the relationship with abnormal stock returns and business accounting information is also positive for mispriced stock (Aabo et al., 2017). There are additional studies examining how IVOL is affected by firm-specific characteristics; for instance, IVOL is significantly more pronounced in the introduction and decline phases of the firm life cycle and significantly muted in the growth and maturity phases (Hasan & Habib, 2017). Furthermore, Cao et al. (2022) demonstrated that in China, high levels of IVOL are associated with increased risk of crashing in the company's stock price.
Additionally, research has also shown how other variables interact with IVOL in significant ways, which is important for the current study. In Walkshäusl's (2014) analysis of the interactions between IVOL and MAX over the last month, he concluded that the negative correlation between these two factors does not exist when the MAX is considered for European markets. Wijayani et al. (2023), in their analysis of the interactions between IVOL and company size on the Indonesia Stock Exchange, found significant negative relationships between IVOL and profitability, company size, and price-earnings ratios.
Recent academic contributions have further explored the complexities of the idiosyncratic volatility (IVOL) puzzle across diverse global markets, providing fresh insights into its drivers and persistence Khurram et al. (2025) used data from the Pakistani equity market to show that as institutional investors become increasingly involved in a particular market through their expanding numbers, the negative IVOL premium the marketplace experiences will become increasingly diminished; thus the effect of the institutional investor becomes a mispricing driven by sentiment and not a risk factor.. In contrast, Enescu and Szeles (2026) showed that in European equity markets, institutional investor ownership, particularly among transient (i.e., frequently buying and selling) investors, creates an increasingly destabilizing environment, contributing to higher levels of IVOL. Their study provides evidence that institutional investors play an important role in contributing to greater IVOL, but that firm-specific characteristics moderate this instability, with characteristics related to firm profitability (providing stability) and firm leverage (increasing instability) having the largest impact on the IVOL attributable to institutional investors.
In addition to the structural research above, researchers have been able to demonstrate a growing role for risk perception and methodological development in advancing our understanding of the IVOL puzzle. Perera et al. (2025) found that the IVOL effect persists across asset classes and is most pronounced for stocks with greater risk exposure; in particular, they noted that investor inattention is critical for these stocks to experience the IVOL effect. In furtherance of this more granular-level analysis, Liu and Zhu (2025) developed a framework that decomposes IVOL into "good" and "bad" elements. Their results indicate that asymmetries in the expected "good minus bad" volatility as compared to traditional forecasting models, have a better ability to predict the future returns than does IVOL, leading to the conclusion that the IVOL effect is strongly related to items such as conditional return asymmetries based on underlying firm characteristics (e.g., ROE and momentum).
Method
Data
The Egyptian Stock Market is one of the oldest in the Middle East, established in the nineteenth century. The Alexandria Stock Market was established in 1883, followed by the Cairo Stock Market in 1903. At the end of June 2022, there were 224 companies listed on the Egyptian stock market.[1] The sample includes some stocks listed on the EGX100 index from June 2018 to June 2022. This index serves as a benchmark for the top 100 constituents of the Egyptian Stock Market, prioritized by trading turnover and market liquidity, and includes the EGX30 and EGX70 Indices.
Not all stocks are chosen. The following requirements have to be met:
- Only Stocks listed in the EGX100 index will be used.
- Stocks of financial institutions and banks are excluded. Because of the difference in the financial nature of these institutions from non-financial companies
- Each stock in the sample must have at least 15 continuous daily price observations every month.
The final sample consists of 80 stocks from the EGX100 index in the Egyptian market, after applying the required filtering criteria.
This study uses daily stock return to calculate the extreme positive daily return in the past month (MAXi,t), the average of the three highest daily returns in the past month (MAX3), short-term reversal (REVi,t), momentum (MOMi,t), market beta (BETAi,t), market capitalization (SIZEi,t), and idiosyncratic volatility (IVOLi,t) on a monthly basis.
Methodology
Following the methods of Bali et al. (2011), (MAXi,t) is the extreme positive daily return in the past month (month t-1) for the firm i. An alternative measure, MAX3, is computed as the mean of the three largest daily returns observed for each stock in the previous month (month t-1).
The following regression model is used to calculate (IVOLi,t) and market beta (BETAi,t). For the estimation of the equation, the daily stock returns for (month t-1) were used.

Where: (Rit) and (Rmt) are the return on stock i and the market portfolio on day t, respectively. (Rf) is the risk-free rate on day t, ßmt is the market beta (BETAi,t), (εit) is the error term, and (α) is the intercept. Following Eiling (2006), the idiosyncratic volatility (IVOL) of stock i in month t is the standard deviation of the residuals (εit) in equation (1).
Following Bali et al. (2011), a number of variables are also included in the regression models as control variables: Short-term reversal (REVi,t), Momentum (MOMi,t), Market Beta (BETAi,t), and market capitalization (SIZEi,t).
Following the work of Jegadeesh (1990) and Lehmann (1990), short-term reversal (REVi,t) represents the stock's return from the previous month. In other words, The (REVi,t) should indicate the monthly return in (month t-1) if the expected return is in (month t).
MOMi,t is the cumulative monthly returns of stock 𝑖 over the past 11 months starting from month t-12 to month t-1, following Jagadeesh and Titman (1993).
SIZE,t-1 is calculated by Log of the average market capitalization of stock i at the end of the previous month (month t-1)
The MAX and IVOL effect on the Egyptian stock market is quantified using the regression model below:
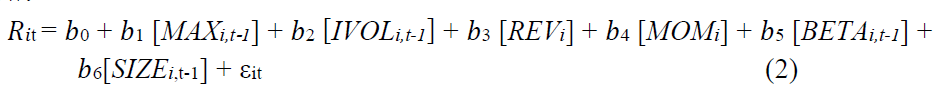
Results
Table 1 presents the descriptive statistics for all variables used for this test. (MAXt-1) is the extreme positive daily return in the past month, (MAX3 t-1) is the average of the three highest daily returns in the past month, (REV) is short-term reversal, (MOM) is the momentum, (BETAt-1) is the market beta, (SIZEit-1) is the natural logarithm of market capitalization over the past month, and (IVOLt-1) is the idiosyncratic volatility.
Table 1
Descriptive Statistics of MAX and Other Control Variables in the Egyptian Stock Market
|
|
M |
SE |
Mdn |
SD |
Var. |
Kurt. |
Skew. |
Range |
Min. |
Max. |
|
RETURN |
0 |
.01 |
-.01 |
.08 |
.01 |
0.85 |
-0.34 |
.4 |
-.24 |
.17 |
|
MAX t-1 |
.06 |
.01 |
.05 |
.05 |
0 |
17.99 |
4.09 |
.32 |
.02 |
.33 |
|
MAX3 t-1 |
.04 |
0 |
.04 |
.01 |
0 |
-0.01 |
-0.37 |
.03 |
.03 |
.06 |
|
IVOL t-1 |
.03 |
0 |
.03 |
.01 |
0 |
2.5 |
0.35 |
.04 |
.01 |
.05 |
|
REV |
0 |
.01 |
-.01 |
.08 |
.01 |
0.87 |
-0.36 |
.4 |
-.24 |
.17 |
|
MOM |
.31 |
.01 |
.33 |
.1 |
.01 |
0.63 |
-0.96 |
.43 |
.03 |
.46 |
|
BETA t-1 |
-.14 |
.03 |
-.14 |
.2 |
.04 |
0.43 |
0.03 |
.97 |
-.58 |
.39 |
|
SIZE t-1 |
.69 |
.01 |
.7 |
.06 |
0 |
1.13 |
-0.99 |
.25 |
.55 |
.8 |
Table 2 displays the time-series averages of the slope coefficients, computed over the 48 months from June 2018 to June 2022. The t-values are presented in parentheses. The key findings indicate that the coefficient associated with Idiosyncratic Volatility (IVOLt-1) is positive and statistically significant throughout the study period, with a coefficient of 4.07 (t = 2.72). This result suggests that stocks with higher firm-specific volatility tend to yield higher subsequent returns. This observed positive association is supportive of the findings reported by several scholars (e.g., Fu, 2009; Qadan, 2019), yet it clearly runs contrary to the prevailing negative relationship documented by Ang et al. (2006) and Drew et al. (2004) for the IVOL puzzle. Furthermore, the results established a significantly inverse relationship between Size (SIZEt-1) and the expected stock return, registering a coefficient of -.45 (t = -2.40). This evidence strongly confirms the widely accepted Size Effect, consistent with the seminal work of Fama & French (1992) and subsequent studies such as Keim (1982) and Chui and Wei (1998). Conversely, the coefficients for the remaining control variables lack statistical significance.
Cross-sectional Regression Results for Only One Variable, Using MAX, IVOL, and Other Control Variables
|
MAX t-1 |
MAX3 t-1 |
IVOL t-1 |
REV |
MOM |
BETA t-1 |
SIZE t-1 |
|
0.16 |
2.08 |
4.07*** |
-0.07 |
0.16 |
-0.03 |
-0.45** |
|
(0.78) |
(1.34) |
(2.72) |
(-0.47) |
(1.55) |
(-0.63) |
(-2.40) |
Note. Table 2 presents the cross-sectional regressions with only one variable, using MAX, IVOL, and other control variables. Cross-sectional regression of returns on MAX and other control variables at the firm level per month is used. The time-series results of the slope coefficients and their corresponding t-statistics are reported in each row. The symbols *, **, and ***represent significance levels at the 10%, 5%, and 1% level, respectively.
Table 3 presents both multivariate and bivariate cross-sectional regressions with MAX and other control variables. The analysis indicates that the MAX effect loses explanatory power once the control variables are incorporated into the regression framework, either individually with MAX or simultaneously after controlling for all four variables (excluding IVOL and MAX3t-1). This is empirically evident in the last row of the table, where the coefficient for MAXt-1 is statistically insignificant (.01) (t = .08). Furthermore, the coefficient for MAXt-1 is also insignificant when tested in bivariate regressions with the other control factors. Conversely, the SIZEt-1 factor maintains its significantly negative relationship to expected returns, with a coefficient of -0.4223 (t = -1.99), reaching a 5% significance level, even in the presence of MAXt-1. This observed disappearance of the MAX effect suggests that, in the context of this specific market and period, the predictive power of MAX is largely absorbed by the other control variables included in the model. This finding contrasts with research that confirms the independence and persistence of the negative MAX effect even after controlling for various factors (Annaert et al., 2013; Bali et al., 2011), as well as studies that confirm its strength in emerging markets (Zhong & Gray, 2016).
Bivariate and Multivariate Cross-Sectional Regressions Using MAX alongside Several Control Variables
|
MAX t-1 |
.13 |
.11 |
.15 |
.10 |
.24 |
.11 |
||||||
|
(.63) |
(.58) |
(.74) |
(.50) |
(1.16) |
(.58) |
|||||||
|
|
BETA t-1 |
-.02 |
SIZE t-1 |
-.45*** |
REV |
-.06 |
MOM |
.15 |
MAX3 t-1 |
2.53 |
IVOL t-1 |
3.99*** |
|
(-.44) |
(-2.31) |
(-.42) |
(1.41) |
(1.59) |
(2.64) |
|||||||
|
.01 |
-.05 |
-.42** |
-.10 |
.10 |
|
|||||||
|
(.08) |
(-.93) |
(-1.99) |
(-.68) |
(.89) |
||||||||
Note. Table 3 presents the multivariate and bivariate cross-sectional regressions using MAX alongside several control variables. This study used the cross-sectional regression of returns on MAX and other control variables at the firm level per month. The time-series results of the slope coefficients and their corresponding t-statistics are reported in each row. The last row in the table represents the cross-sectional regression analysis after excluding IVOL and MAX3 t-1. The symbols *, **, and ***represent significance levels at the 10%, 5%, and 1% level, respectively.
Table 4 displays the outcomes of both bivariate and multivariate cross-sectional regressions, with IVOL and other control variables. The study used monthly firm level cross sectional regressions to examine the impact of IVOL and other control variables on stock returns. The time-series results of the slope coefficients and their corresponding t-statistics are reported in each row. The findings show that IVOLt-1 has a positive, statistically significant effect when the other six control variables (BETA, SIZE, REV, MOM, MAX3t-1, and MAXt-1) are taken into account individually with IVOL, as evidenced by the high significance levels reported in the table. However, after adding all five control variables simultaneously (excluding MAX3t-1 from the control variables), the IVOL coefficient becomes insignificant in the last row of the table. This loss of significance suggests that the predictive power of IVOL is highly conditional and sensitive to the inclusion of other known factors, potentially indicating an overlap in the information captured by these variables. This result supports the notion that the relationship between IVOL and returns is fragile and subject to contextual factors, strengthening the argument made by Bali and Cakici (2008), who found no robustly significant relation between IVOL and expected returns. Moreover, the result aligns with Walkshäusl's (2014) conclusion that the puzzle of the negative IVOL relation no longer exists after controlling for MAXt-1, suggesting a strong interaction between volatility measures.
Bivariate and Multivariate Cross-sectional Regressions Using IVOL alongside Several Control Variables
|
IVOL t-1 |
4.05*** |
3.05** |
4.04*** |
3.96*** |
4.31*** |
3.99*** |
|||||||
|
(2.69) |
(1.85) |
(2.64) |
(2.15) |
(2.30) |
(2.63) |
||||||||
|
|
BETA t-1 |
-.03 |
SIZE t-1 |
-.29 |
REV |
-.01 |
MOM |
.01 |
MAX3 t-1 |
-.40 |
MAX t-1 |
.11 |
|
|
(-.63) |
(-1.40) |
|
(-.13) |
(.10) |
(-.2) |
(.59) |
|||||||
|
2.76 |
-.04 |
-.33 |
-.03 |
.00 |
.03 |
|
|||||||
|
(.76) |
(-.87) |
(-1.49) |
(.86) |
(.03) |
(.01) |
||||||||
Note. Table 4 presents the multivariate and bivariate cross-sectional regressions using IVOL alongside several control variables. This study used the cross-sectional regression of returns on IVOL and other control variables at the firm level per month. The time-series results of the slope coefficients and their corresponding t-statistics are reported in each row. The last row in the table represents the cross-sectional regression analysis after excluding MAX t-1. The symbols *, **, and ***represent significance levels at the 10%, 5%, and 1% level, respectively.
Table 5 presents both multivariate and bivariate cross-sectional regressions with MAX3t-1 and other control variables. The results demonstrate that the MAX3 effect is not statistically significant when the other five variables (IVOL, REV, MOM, BETA, and SIZE) are taken into account, either individually with MAX3t-1 or simultaneously after controlling for all five variables (excluding MAXt-1). The final row of the table, which represents the cross-sectional regression analysis after controlling for all factors, shows that the coefficient for MAX3t-1 is extremely small (.03) and its t-statistic (.01) indicates it is not statistically significant. Crucially, this lack of explanatory power for MAX3t-1 aligns with the findings for MAXt-1 reported in Table 3, suggesting a general fragility of extreme return measures in predicting subsequent returns in this specific market context, even when other known risk and anomaly factors are introduced. This result contradicts the robust and persistent negative MAX effects documented by pioneering studies (Annaert et al., 2013; Bali et al., 2011), which often find that both MAX and MAX3 maintain their significance and predictive power even in multivariate settings, suggesting a strong contextual dependence of the MAX anomaly in the market under study. Conversely, the IVOLt-1 factor retains its strong positive significance (t = 2.31), which is statistically significant at the 1% level, and the SIZEt-1 factor also remains significant (t = -2.13), which is statistically significant at the 5% level, confirming their roles as persistent drivers of stock returns even in the presence of MAX3t-1.
Bivariate and Multivariate Cross-sectional Regressions Using MAX3 alongside Several Control Variables
|
MAX3 t-1 |
-.40 |
2.42 |
1.91 |
2.12 |
1.33 |
|||||
|
(-.22) |
(1.51) |
(1.25) |
(-1.44) |
(.87) |
||||||
|
|
IVOL t-1 |
4.32*** |
REV |
-.12 |
MOM |
0.15 |
BETA t-1 |
-0.04 |
SIZE t-1 |
-0.42*** |
|
(2.31) |
(-.84) |
|
(1.48) |
(-0.7) |
(-2.13) |
|||||
|
.03 |
2.76 |
-.03 |
.006 |
-.0483 |
-.332 |
|||||
|
(.01) |
(.76) |
(-.16) |
(.03) |
(-.87) |
(-1.49) |
|||||
Note. Table 5 presents the multivariate and bivariate cross-sectional regressions using MAX3 alongside several control variables after excluding MAX t-1. This study used the cross-sectional regression of returns on MAX3t-1 and other control variables at the firm level per month. The time-series results of the slope coefficients and their corresponding t-statistics are reported in each row. The last row in the table represents the cross-sectional regression analysis after excluding MAX t-1. The symbols *, **, and ***represent significance levels at the 10%, 5%, and 1% level, respectively.
Table 6 presents both multivariate and bivariate cross-sectional regressions with MAX, IVOL, and other control variables (REV, MOM, BETAt-1, and SIZEt-1). The results show that the MAX effect is not statistically significant when the other four variables are taken into account, along with MAXt-1 and IVOLt-1, as indicated by the final regression model in the table (coefficient .05, t = .23). This finding reinforces the conclusion drawn from Table 3 regarding the general lack of robustness of the MAX anomaly in this specific market context. Moreover, the results concerning IVOLt-1 highlight its strong dependence on firm characteristics. IVOLt-1 still has a positive and statistically significant effect (e.g., 3.99***) when controlling only for the MAX effect or when controlling for REV, MOM, and BETAt-1. However, after adding SIZEt-1, the IVOL coefficient becomes insignificant (2.85 (1.35). This crucial observation suggests a strong interaction and overlap between the effects of IVOL و SIZE. The disappearance of the IVOL significance upon the inclusion of SIZE supports the hypothesis that the information captured by IVOL might, to a certain extent, be proxied by the firm’s size, or that the IVOL-return relationship is primarily driven by smaller firms (Drew et al., 2004). Conversely, the SIZEt-1 coefficient remains negative (.32) and is on the borderline of statistical significance (1.46), confirming the persistence of the Size effect as the most stable factor in the model.
Bivariate and Multivariate Cross-sectional Regressions Using MAX, IVOL alongside Several Control Variables
|
MAX t-1 |
IVOL t-1 |
REV |
MOM |
BETA t-1 |
SIZE t-1 |
|
.11 |
3.99*** |
|
|
|
|
|
(.58) |
(2.63) |
|
|
|
|
|
.11 |
3.97*** |
-.01 |
|
|
|
|
(.57) |
(2.56) |
(-.09) |
|
|
|
|
.11 |
3.91** |
-.01 |
.006 |
|
|
|
(.54) |
(1.95) |
(-.10) |
(.04) |
|
|
|
.08 |
3.84** |
-.01 |
.01 |
-.02 |
|
|
(.38) |
(1.89) |
-(.08) |
(.10) |
-(.48) |
|
|
.05 |
2.85 |
-.02 |
-.00 |
-.04 |
-.32 |
|
(.23) |
(1.35) |
-(.18) |
-(.017) |
-(.76) |
-(1.46) |
Note. Table 6 presents the multivariate and bivariate cross-sectional regressions using MAX, IVOL alongside several control variables. This study used the cross-sectional regression of returns on MAX, IVOL, and other control variables at the firm level per month. The time-series results of the slope coefficients and their corresponding t-statistics are reported in each row. The last row in the table represents the cross-sectional regression analysis after excluding MAX3 t-1. The symbols *, **, and ***represent significance levels at the 10%, 5%, and 1% level, respectively.
Table 7 presents both multivariate and bivariate cross-sectional regressions with MAX3t-1, IVOLt-1, and other control variables. The results clearly show that the MAX3 effect is not statistically significant when the other four variables were taken into account with MAX3 and IVOL. This further reinforces the conclusion from Table 5 regarding the general lack of explanatory power for the extreme return measures (coefficient .03, t = .01) in the final regression. Moreover, the findings concerning IVOLt-1 highlight its conditional significance. IVOLt-1 still has a positive and statistically significant effect (t = 2.30) when controlling for the MAX3 effect or when controlling for REV (t = 2.10). However, after adding MOM, BETAt-1, and SIZEt-1, the IVOL coefficient becomes insignificant (2.761, t = .76). This robust observation strongly indicates that the information captured by IVOL is largely subsumed by the combined effect of size, momentum, and systematic risk (BETA). This supports the argument that the IVOL-return relationship is highly sensitive to the full set of factors included in the model, aligning with the premise that the IVOL puzzle might be explained by its covariance with other market anomalies (Ang et al., 2006; Drew et al., 2004).
Bivariate and Multivariate Cross-sectional Regressions Using MAX3, IVOL alongside Several Control Variables
|
MAX3 t-1 |
IVOL t-1 |
REV |
MOM |
BETA t-1 |
SIZE t-1 |
|
-.40 |
4.31*** |
|
|
|
|
|
-(.22) |
(2.30) |
|
|
|
|
|
-.37 |
4.2919*** |
-.00 |
|
|
|
|
-(.18) |
(2.104) |
-(.03) |
|
|
|
|
-.27 |
4.13 |
-.01 |
.01 |
|
|
|
-(.09) |
(1.16) |
-(.06) |
(.05) |
|
|
|
-.13 |
3.92 |
-.01 |
.02 |
-.03 |
|
|
-(.04) |
(1.09) |
-(.06) |
(.12) |
-(.60) |
|
|
.03 |
2.76 |
-.03 |
.00 |
-.04 |
-.33 |
|
(.01) |
(.76) |
-(.16) |
(.03) |
-(.87) |
-(1.49) |
Note. Table 7 presents the multivariate and bivariate cross-sectional regressions using MAX3, IVOL alongside several control variables. This study used the cross-sectional regression of returns on MAX3, IVOL, and other control variables at the firm level per month. The time-series results of the slope coefficients and their corresponding t-statistics are reported in each row. The last row in the table represents the cross-sectional regression analysis after excluding MAX3 t-1. The symbols *, **, and ***represent significance levels at the 10%, 5%, and 1% level, respectively.
Conclusion
This paper investigated the presence of both the IVOL and MAX effects in the Egyptian Stock Market from June 2018 to June 2022. The method of Bali et al. (2011) was followed, where (MAXi,t) was used as a proxy for the extreme positive daily return in the past month (month t-1) for the firm and (IVOLi,t) was used as a proxy for Idiosyncratic Volatility. (MAX3) was used as an alternative variable for the average of the three highest daily returns in the past month (month t-1). A number of control variables were also included in the regression models; these variables are Short-term reversal (REVi,t), Momentum (MOMi,t), Market Beta (BETAi,t), and market capitalization (SIZEi,t).
The results showed that the relationship between the MAX effect and the expected return is not significant when the other six variables were taken into account either individually with MAX or after controlling for all six variables simultaneously. Therefore, there is no MAX effect on the Egyptian Stock Market. The results also showed that the IVOL effect is significantly positive, indicating that stocks with higher IVOL tend to have significantly higher future returns. These results run contrary to those of Ang et al. (2006), who concluded that stocks with higher IVOL tend to have significantly lower future returns. Therefore, this study indicates that investors in the Egyptian Stock Market tend to buy stocks with a higher IVOL in the hope of getting higher returns; therefore, investors must be more careful in choosing these stocks because this indicates higher risk and is not proportionate to the expected return.
This study has some limitations that could be overcome in future studies. It only examines companies listed on the EGX100 index; besides that, the study period was 5 years. Therefore, it is recommended that future researchers expand the research period beyond 5 years. In addition, using a larger sample size could produce better results. The study also recommends that future researchers add additional factors to the model, such as stock liquidity, which has a significant impact on expected returns. The results of the study have important implications, especially for investors who want to create suitable portfolios by correctly assessing assets and policymakers who seek to mitigate misvaluations by investors.
Funding
No funding was received for this research.
Author Contributions
The author confirms sole responsibility for the following: study conception and design, data collection, analysis and interpretation of results, and manuscript preparation.
Conflict of Interest
The authors declare no conflicts of interest
Generative AI Use Disclosure Statement
During the preparation of this work, the author used Gemini only to improve the English phrasing and summarize minor points within the manuscript. After using this tool, the author reviewed and edited the content to ensure accuracy and takes full responsibility for the final content of the publication.
Data Availability Statement
Data will be available on request from the authors.
Acknowledgments
Not applicable.
References
Aabo, T., Pantzalis, C., & Park, J. C. (2017). Idiosyncratic volatility: an indicator of noise trading? Journal of Banking and Finance, 136–151. https://doi.org/10.1016/j.jbankfin.2016.11.003
Ang, A., Hodrick, R. J., Xing, Y., & Zhang, X. (2006). The cross‐section of volatility and expected returns. The Journal of Finance, 61(1), 259–299. https://doi.org/10.1111/j.1540-6261.2006.00836.x
Annaert, J., De Ceuster, M., & Verstegen, K. (2013). Are extreme returns priced in the stock market? European evidence. Journal of Banking and Finance, 3401–3411. https://doi.org/10.1016/j.jbankfin.2013.05.015
Bali, T. G., & Cakici, N. (2008). Idiosyncratic volatility and the cross-section of expected returns. The Journal of Financial and Quantitative Analysis, 43(01), 29–58. https://doi.org/10.1017/S002210900000274X
Bali,T. G., Cakici, N., & Whitelaw, R. F. (2011). Maxing out: stocks as lotteries and the cross-section of expected returns. Journal of Financial Economics, 99(2), 427–446. https://doi.org/10.1016/j.jfineco.2010.08.014
Bi, J., Gui, P., & Zhu, Y. (2022). Large transactions and the Max Effect: Evidence from China. Pacific-Basin Finance Journal, 75, 101852. https://doi.org/10.1016/j.pacfin.2022.101852
Brunnermeier, M. K., Gollier, C., & Parker, J. A. (2007). Optimal beliefs, asset prices, and the preference for skewed returns. The American Economics Review, 97(2), 159–165. https://doi.org/10.1257/aer.97.2.159
Cao, J., Wen, F., Zhang, Y., Yin, Z., & Zhang, Y. (2022). Idiosyncratic volatility and stock price crash risk: Evidence from China. Finance Research Letters, 44, 102095. https://doi.org/10.1016/j.frl.2021.102095
Chui, A. C., & Wei, K. J. (1998). Book-to-market, firm size, and the turn-of-the-year effect: Evidence from Pacific-Basin emerging markets. Pacific-Basin finance journal, 6(3-4), 275-293. https://doi.org/10.1016/S0927-538X(98)00013-4
Dimitry, R. A., & Nugroho, B. Y. (2023). Analysis of the effect of MAX return on expected return in Indonesian stocks exchange. International Journal of Arts and Social Science, 6(7), 154–160.
Drew, M. E., Naughton, T., & Veeraraghavan, M. (2004). Is idiosyncratic volatility priced? International Review of Financial Analysis, 13(3), 349–366. https://doi.org/10.1016/j.irfa.2004.02.027
Egginton, J., & Hur, J. (2018). The robust “maximum daily return effect as demand for lottery” and “idiosyncratic volatility puzzle.” Journal of Empirical Finance, 47, 229–245. https://doi.org/10.1016/j.jempfin.2018.03.001
Eiling, E. (2006). Can non-tradable assets explain the apparent premium for idiosyncratic risk? The case of industry-specific human capital [Unpublished working paper, Tilburg University, Netherlands].
Enescu, A. G., & Szeles, M. R. (2026). Institutional investors, dividend policy, and idiosyncratic volatility: Evidence from European equity markets. International Journal of Financial Studies, 14(2), 50. https://doi.org/10.3390/ijfs14020050.
Fama, E. F., & French, K. R. (1993). Common risk factors in the returns on stocks and bonds. Journal of financial economics, 33(1), 3-56. https://doi.org/10.1016/0304-405X(93)90023-5
Fu, F. (2009). Idiosyncratic risk and the cross-section of expected stock returns. Journal of Financial Economics, 91(1), 24–37. https://doi.org/10.1016/j.jfineco.2008.02.003
Hasan, M. M., & Habib, A. (2017). Firm life cycle and idiosyncratic volatility. International Review of Financial Analysis, 50, 164–175. https://doi.org/10.1016/j.irfa.2017.01.003
Huang, A. G. (2009). The cross-section of cashflow volatility and expected stock returns. Journal of Empirical Finance, 16(3), 409–429. https://doi.org/10.1016/j.jempfin.2009.01.001
Hur, J., & Singh, V. (2016). Cross‐section of expected returns and Extreme returns: The role of investor attention and risk preferences. Financial Management, 46(2), 409–431. https://doi.org/10.1111/fima.12145
Jegadeesh, N. (1990). Evidence of predictable behavior of security returns. The Journal of finance, 45(3), 881-898. https://doi.org/10.1111/j.1540-6261.1990.tb05110.x
Kashif, M., & Leirvik, T. (2022). The Max Effect in an oil exporting country: The case of Norway. Journal of Risk and Financial Management, 15(4), 154. https://doi.org/10.3390/jrfm15040154
Keim, D. B. (1983). Size-related anomalies and stock return seasonality: Further empirical evidence. Journal of financial economics, 12(1), 13-32. https://doi.org/10.1016/0304-405X(83)90025-9
Khurram, M. U., Ali, F., & Ülkü, N. (2025). Idiosyncratic volatility and the cross-section of abnormal returns in Pakistan: Evidence from a country with religious bans on lotteries and substantive institutional investor participation. International Review of Economics & Finance, 98, 103883. https://doi.org/10.1016/j.iref.2025.103883
Lehmann, B. N. (1990). Fads, martingales, and market efficiency. The Quarterly Journal of Economics, 105(1), 1-28. https://doi.org/10.2307/2937816
Liu, Y., & Zhu, Y. (2025). Good idiosyncratic volatility, bad idiosyncratic volatility, and the cross-section of stock returns. Journal of Banking & Finance, 170, 107343. https://doi.org/10.1016/j.jbankfin.2024.107343
Perera, K., Kuruppuarachchi, D., Kumarasinghe, S., & Suleman, M. T. (2025). Climate risk and the idiosyncratic volatility puzzle. Applied Economics, 57(27), 3689–3708. https://doi.org/10.1080/00036846.2024.2337816
Qadan, M. (2019). Risk appetite, idiosyncratic volatility, and expected returns. International Review of Financial Analysis, 65, 101372. https://doi.org/10.1016/j.irfa.2019.101372
Seif, M., Docherty, P., & Shamsuddin, A. (2018). Limits to arbitrage and the Max Anomaly in Advanced Emerging Markets. Emerging Markets Review, 36, 95–109. https://doi.org/10.1016/j.ememar.2018.03.004
Stambaugh, R. F., YU, J., & Yuan, Y. (2015). Arbitrage asymmetry and the idiosyncratic volatility puzzle. The Journal of Finance, 70(5), 1903–1948. https://doi.org/10.1111/jofi.12286
Walkshäusl, C. (2014). The max effect: European evidence. Journal of Banking & Finance, 42, 1–10. https://doi.org/10.1016/j.jbankfin.2014.01.020
Wijayani, D. I., Walidina, A. R., Ismawanto, T., & Kusuma Wardani, D. A. (2023). The role of firm size, price earning ratio, and profitability to idiosyncratic volatility: Evidence from banking industry in Indonesia. Jurnal Informasi, Perpajakan, Akuntansi, Dan Keuangan Publik, 18(2), 239–256. https://doi.org/10.25105/jipak.v18i2.17167
Wu, J., Chimezie, E. P., Nartea, G. V., & Zhang, J. (2019). Extreme returns and the idiosyncratic volatility puzzle: African evidence. Applied Economics, 51(58), 6264–6279. https://doi.org/10.1080/00036846.2019.1631442
Zhong, A., & Gray, P. (2016). The max effect: An exploration of risk and mispricing explanations. Journal of Banking and Finance, 65, 76–90. https://doi.org/10.1016/j.jbankfin.2016.01.007
[1]- http://www.egx.com.eg

Page 1 of
Download Count : 22
Visit Count : 396
Keywords
Maximum Daily Return; Idiosyncratic Volatility; Egyptian Stock Exchange; Cross-Sectional Regression Analysis

Author(s) Information

How to cite this article
Abd-Allah, M. H. (2026). Extreme returns and idiosyncratic volatility: Evidence from the Egyptian stock exchange. New Challenges in Accounting and Finance, 15, 1-14. https://doi.org/10.32038/ncaf.2026.15.01
Funding
No funding was received for this research.
Author Contributions
The author confirms sole responsibility for the following: study conception and design, data collection, analysis and interpretation of results, and manuscript preparation.
Conflict of Interest
The authors declare no conflicts of interest
Generative AI Use Disclosure Statement
During the preparation of this work, the author used Gemini only to improve the English phrasing and summarize minor points within the manuscript. After using this tool, the author reviewed and edited the content to ensure accuracy and takes full responsibility for the final content of the publication.
Data Availability Statement
Data will be available on request from the authors.
Acknowledgments
Not applicable.
Open Access
This article is licensed under a Creative Commons Attribution 4.0 International License, which permits use, sharing, adaptation, distribution and reproduction in any medium or format, as long as you give appropriate credit to the original author(s) and the source, provide a link to the Creative Commons license, and indicate if changes were made. You may view a copy of Creative Commons Attribution 4.0 International License here: http://creativecommons.org/licenses/by/4.0/